
- June 20, 2024
- June 20, 2024
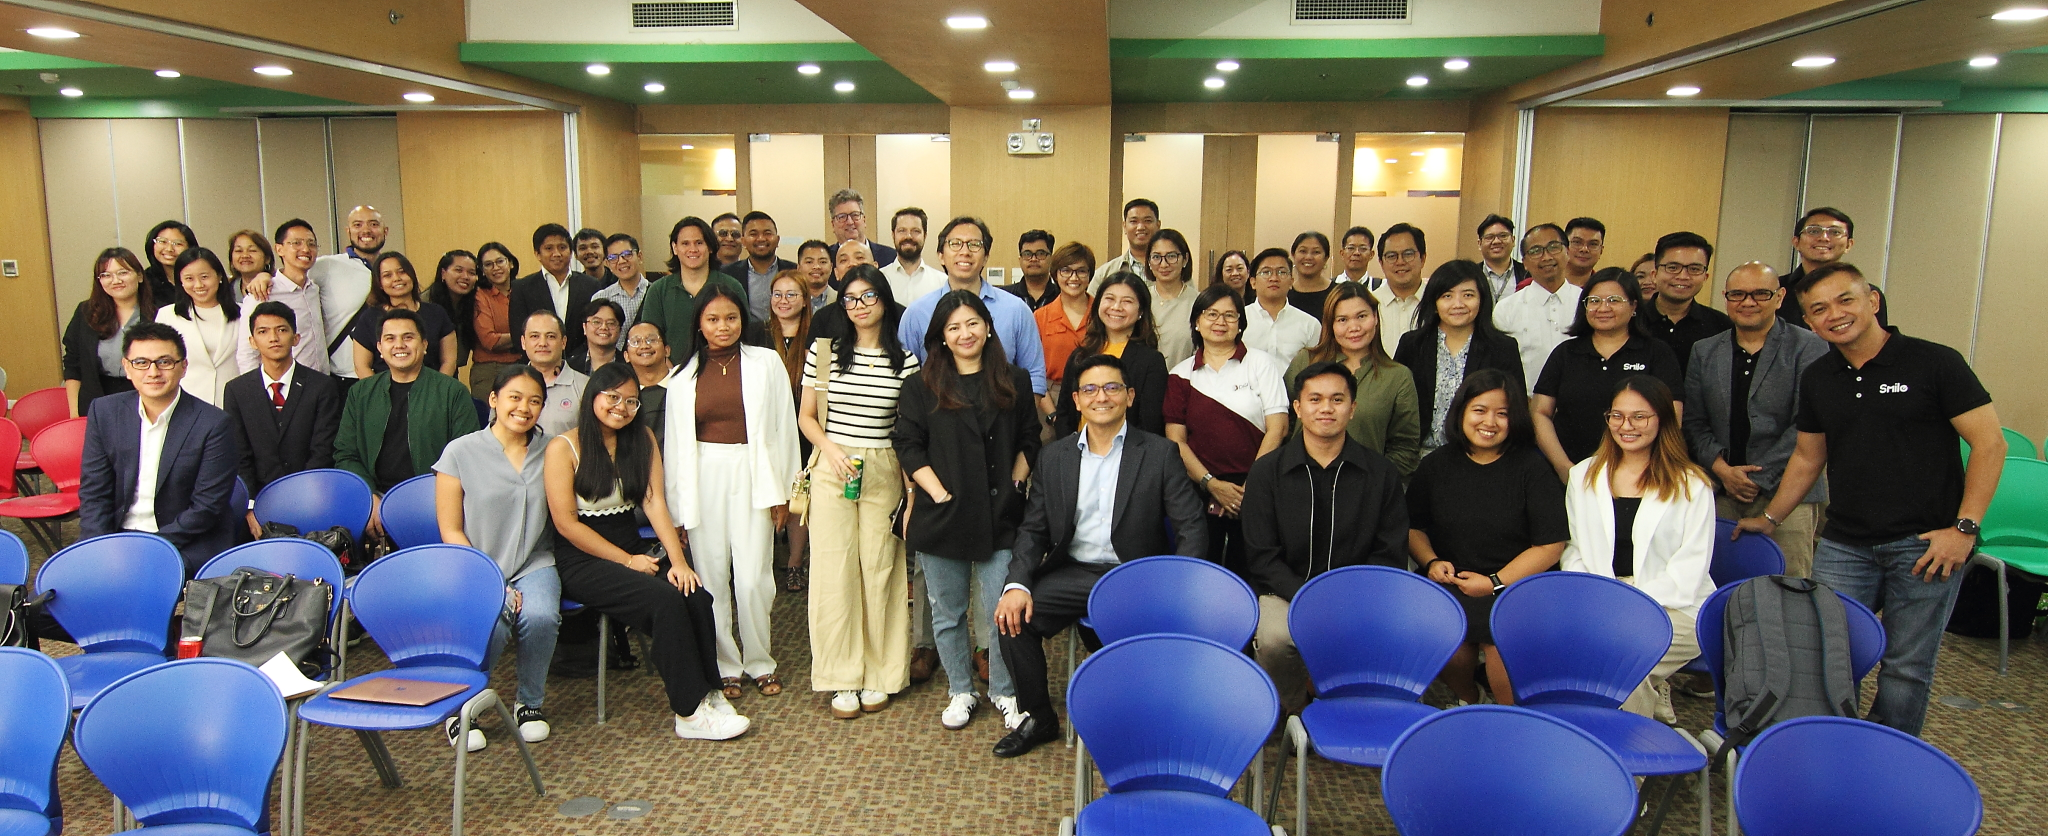
FPH x Smile API May Mixer - Shaping Fintech To A Consent-Driven Future
This year’s May Mixer was made possible through the partnership of Fintech Philippines Association and Smile API, a fintech company known for providing real-time, verified, and user-consented employment data for financial institutions and HR departments. The event featured a distinguished panel of industry leaders who shared their insights on financial literacy, the role of rural banks, consumer trust, and data privacy. During the discussion, National Privacy Commission’s Deputy Commissioner Atty. Leandro Aguirre emphasized the crucial role of data privacy and the need for consent-driven data management. He stated, "If we hear about you, then you're not exactly doing a great job. If you're successful, it means the customer trusts you. The moment we hear about you, something's gone wrong." - Aguirre also highlighted the responsibility of companies to educate and empower individuals about their data rights, ensuring transparency and trust between both parties.Rafael Amparo shared valuable insights on the role of rural banks in achieving financial inclusion. He highlighted the significance of developing strong relationships to better understand and serve rural communities. Rural banks, he noted, act as vital links between rural communities and government initiatives, with him saying “Results have been moderate, but we did this with them (pertaining to government institutions). Ties with the government are a lot deeper than what people would believe.” while discussing how DTI’s partnership with the International Fund for Agricultural Development (IFAD) has provided local MSMEs with secured funding needed to grow their businessesAmparo further discusses the massive potential of neobanks in the Philippine market, noting their ability to leverage technology and extend financial services to underserved communities like the rural areas. He also pointed out that only few financial institutions can match the reach and understanding of rural banks, making them crucial for achieving financial inclusion. The rise of neobanks presents a challenge to traditional financial institutions, highlighting the need to expand their scope of service and create partnerships with government agencies & other institutions to effectively reach these markets.“There are places that don't exist from a banking perspective, yet we do know that a lot of these business owners are creating economies here.” - Marius Mare on rural businesses and their economies - Sybrin’s Marius Mare was also able to share his experiences from working in South Africa, where he highlighted the importance of tracking business activities in rural areas to which they plan to integrate them into the broader financial system to give them more opportunities. Mare emphasized that there is a need for reliable data sources in the country and advocated for improved methodologies & accuracy on data gathering, including enhancements in government data systems.The discussion also featured Christian Lauron talking about the critical role of proper data handling to achieve financial inclusion. When discussing credit score assessments, Lauron states that “... models should be designed to allocate amounts rather than come up with a score for these types of customers”. He addresses the need for financial institutions to utilize various types of data to determine how much rural business owners can borrow aside
- June 20, 2024
- June 20, 2024
- June 18, 2024
- June 18, 2024
What are the 5 Cs of Credit and Why you Should Know Them
The 5 Cs of Credit: An Overview When you apply for a loan or other type of credit, the lender will consider a number of factors to determine your creditworthiness. These factors include your: Character: This refers to your reputation for repaying debts on time and in full. This includes factors such as your payment history, the number of times you've been late on payments, and whether you have any defaults or bankruptcies. Capacity: This refers to your ability to repay the loan. This includes factors such as your income, debt-to-income ratio, and employment status. Capital: This refers to your financial resources. This includes factors such as your savings, investments, and home equity. Collateral: This refers to any assets that you can pledge as security for the loan. It can include things like your car, house, or jewelry. Conditions: This refers to the economic and market conditions at the time of your loan application. It can include factors such as interest rates, inflation, and unemployment. The 5 Cs of credit are all important factors that lenders will consider when making a lending decision. By understanding these factors, you can take steps to improve your creditworthiness and increase your chances of getting approved for a loan at a favorable interest rate. How to Improve Your 5 Cs of Credit - There are a number of things you can do to improve your 5 Cs of credit. Here are a few tips: Character: Pay your bills on time and in full every month. Avoid taking on too much debt. If you have any late payments or defaults, work with a credit counselor to get them resolved. Capacity: Increase your income by getting a better job or starting a side hustle. Decrease your debt-to-income ratio by paying down debt or increasing your income. Learn more about how Smile API's employment data can help you improve your capacity. Capital: Build your savings and investments by setting up a regular savings plan and investing in long-term assets. Increase your home equity by paying down your mortgage. Collateral: If you don't have any collateral, consider getting a cosigner or pledging an asset as security for the loan. Conditions: Monitor economic and market conditions and adjust your spending and saving habits accordingly. FAQs Q: What is the most important C of credit? A: All 5 Cs of credit are important, but character is typically considered the most important. This is because it reflects your willingness and ability to repay your debts. Q: How can I check my credit score? A: You can get a free copy of your credit score from each of the three major credit bureaus in the Philippines (CIBI, CRIF, and TransUnion). Q: What is a good credit score? A: A good credit score is typically considered to be 670 or higher. However, the specific score that you need to get approved for a loan will vary depending on the lender and the type of loan you are applying for. Key Takeaways The 5 Cs of credit are character, capacity, capital, collateral, and conditions. Lenders will consider all 5 Cs of credit when making a lending decision. You can improve your 5 Cs of credit by taking steps to improve your payment histo
- June 18, 2024
- June 18, 2024
- June 11, 2024
- June 11, 2024
What is credit data analysis and why is it important?
Credit data analysis is the process of evaluating data about borrowers to assess their creditworthiness and make informed decisions about loan origination and underwriting. This data can include everything from traditional credit scores and credit reports to more alternative data sources, such as employment history, income, and spending habits. Why is Credit Data Analysis Important? Credit data analysis is important because it helps lenders make better decisions about who to lend to and how much to lend them. By having a more complete picture of a borrower's financial situation, lenders can reduce their risk of default and make more profitable loans. In addition, credit data analysis can help lenders: Identify potential borrowers who may not have a traditional credit score. This can help lenders reach a wider pool of borrowers and increase their lending volume. Make more accurate decisions about loan terms. By understanding a borrower's financial situation, lenders can tailor loan terms to the borrower's specific needs. Reduce the risk of fraud. By verifying a borrower's identity and financial information, lenders can reduce the risk of fraud and identity theft. Techniques in Credit Data Analysis There are a number of different techniques that can be used in credit data analysis. Some of the most common techniques include: Credit scoring: Credit scoring is a statistical model that uses a variety of data points to predict the likelihood that a borrower will default on a loan. Credit report analysis: A credit report is a detailed history of a borrower's credit activity. Lenders can use credit reports to identify any red flags, such as late payments or defaults. Income and employment verification: Lenders can use income and employment verification to confirm a borrower's income and employment status. This information can help lenders assess a borrower's ability to repay a loan. Alternative data analysis: Alternative data is any type of data that is not traditionally used in credit scoring, such as social media data, mobile phone data, and utility bills. Lenders can use alternative data to supplement traditional credit data and get a more complete picture of a borrower's financial situation. Credit Information Management Credit information management is the process of collecting, storing, and using credit data. Lenders use credit information management systems to help them make decisions about loan origination and underwriting. These systems can also be used to track borrowers' credit performance over time. Credit Scoring Models - Credit scoring models are statistical models that use a variety of data points to predict the likelihood that a borrower will default on a loan. These models are used by lenders to make decisions about loan origination and underwriting. There are a number of different credit scoring models, each of which uses its own unique set of data points. FAQs What is the difference between credit data analysis and credit scoring? Credit data analysis is the process of evaluating data about borrowers to assess their creditworthiness. Credit scoring is a statistical model that uses a variety of data points to predict the likelihood that a borrower will default on a loan. What are the benefits of using credit data analysis? Credit dat
- June 11, 2024
- June 11, 2024
- June 3, 2024
- June 3, 2024
Unlocking Value in Fintech: Consumer-Permissioned Data & Open Finance
What is Consumer-Permissioned Data? Consumer-permissioned data refers to financial data that individuals explicitly authorize third-party service providers to access and utilize. This data can include transaction history, account balances, spending patterns, and other relevant financial information. By granting permission, consumers empower fintech companies and financial institutions to develop tailored products and services that meet their specific needs and preferences. - Benefits of Consumer-Permissioned Data in Open Finance 1. Enhanced Personalization: Consumer-permissioned data enables fintechs to gain a comprehensive understanding of individual financial profiles, preferences, and risk appetite. By leveraging this data, they can offer highly personalized recommendations, tailored interest rates, and customized financial products that cater to each customer's unique circumstances. 2. Improved Financial Health: Access to consumer-permissioned data allows fintechs to provide proactive budgeting tools, credit monitoring services, and financial planning assistance. These tools empower individuals to make informed financial decisions, improve their creditworthiness, and achieve their financial goals. 3. Reduced Costs and Increased Efficiency: By eliminating the need for manual data entry and reducing the reliance on costly third-party data providers, open finance with consumer-permissioned data streamlines financial processes and lowers operational costs for both fintechs and consumers. 4. Increased Innovation: Consumer-permissioned data fuels innovation in the fintech industry by enabling the development of new products and services that leverage data insights. This data-driven approach fosters competition and drives down the cost of financial services. 5. Improved Credit Access: By providing alternative data sources, consumer-permissioned data expands the pool of eligible borrowers and improves access to credit for underserved populations. Fintechs can use this data to assess risk more accurately and offer loans to individuals who may have previously been excluded from traditional lending institutions. Smile API: Provider Consumer-Permissioned Data Today Smile API plays a crucial role in enabling Open Finance by empowering individuals with access to their own data. By practicing the principle of Open Finance, Smile API serves as a bridge between individuals and their financial goals. The company believes that access to one's own data is a basic right and is essential for financial inclusion. More data leads to more information, which reduces risk, lowers interest rates, and increases value for workers and society as a whole. This approach helps to improve the quality of life and ensures livelihood, especially for those who are often excluded from traditional financial services. Key Takeaways Consumer-permissioned data is essential for unlocking the full potential of open finance. It empowers consumers with control over their financial data and enables the development of personalized and innovative financial services. Open finance with consumer-permissioned data enhances personalization, improves financial health, reduces costs, fosters innovation, and expands credit access. FAQs What is the difference between consumer-permissioned data and open banking? Open banking is a specific type of open financ
- June 3, 2024
- June 3, 2024
- June 3, 2024
- June 3, 2024
Introducing Smile Checks' New Pricing Model: Tailored to Your Needs
Simplified Individual Purchases The days of locking into bulk purchases are over. Previously, our most basic and cost-efficient check comprised of our Identity and Employment check, coupled with and NBI Clearance check and Reference check, in order to provide you with the most cost-efficient market standard background check. However, if you don't require one or two of these bundled checks, you're locked into this bundle in order to enjoy the greatest savings. Now, you have pick and choose exactly the checks you need. You can still enjoy the great saving and time-saving benefits of our Bundles, but if you need to pick and choose exactly the check you need, you can do so. This means you can enjoy a more cost-effective way to screen candidates, without unnecessary commitments. Each position you hire for is unique, and now, so is the way you can screen for it. Select only the background check reports you require, and leave out the rest. This a la carte approach ensures you're not paying for information you don't need. Credits That Work for You If you prefer planning ahead, our credits system is still in place and will give you the best bang for your buck, up to 50% discount on our background checks. Purchase credits anytime, and use them for any type of check later on. They're your go-to resource, always available and with no expiration date. It's flexibility and peace of mind in one package. If you need to get that background check done, but don't have the budget to purchase credits in bulk just yet, no problem. You can choose exactly the checks you need and pay for it ala carte, instantly. No more waiting for budgets to be approved! - Streamlined Portal Transactions We've upgraded our Portal to make purchasing checks and credits more straightforward. Get what you need instantly without waiting for an invoice – it's efficiency at its best. Pay via e-wallets or direct debit for quickest confirmation. More payment options will be available soon. - Smooth Transition for Current Customers For our valued existing customers, we're ensuring a seamless changeover. Any checks you've previously purchased will be converted into credits within the new system, providing uninterrupted service. You'll be able to use the new credit system immediately. Our goal with this new pricing model is to give you more control and better value, without complicating the process. Smile Checks is here to facilitate your hiring efforts with a system designed around your individual needs. Book a demo with us to learn more about our pricing structure and how Smile Checks works: https://tidycal.com/biancaulan/smile-checks-demo
- June 3, 2024
- June 3, 2024
- June 1, 2024
- June 1, 2024
Best Credit Data Solutions Providers in the Philippines
In the Philippines, accessing credit has become increasingly important for individuals and businesses alike. However, traditional credit scoring systems often rely on limited data, which can lead to inaccurate assessments and missed opportunities for financial inclusion. Credit data solutions address this challenge by providing a more comprehensive and up-to-date view of an individual's or business's creditworthiness. This blog article explores the leading credit data solutions providers in the Philippines, highlighting their services and benefits. By leveraging alternative data sources and advanced analytics, these providers empower lenders and other financial institutions to make more informed credit decisions. Top Credit Data Solutions Providers in the Philippines 1. Smile API Smile API is a fintech company that provides real-time credit data and digital banking solutions. With its network of over 40 million Filipinos, Smile API offers alternative credit data, including proof of employment and income, that can significantly improve credit assessments. By using Smile API's data, lenders can reduce the time and cost of processing while minimizing non-performing loans. 2. Credit Information Corporation (CIC) CIC is the central credit information repository in the Philippines. It collects and maintains credit data from banks, non-bank financial institutions, and other lenders. CIC's report provides a comprehensive view of an individual's or business's credit history, including loans, credit cards, and other financial obligations. 3. TransUnion TransUnion is a global credit reporting agency that operates in the Philippines. Its credit reports include a credit score, payment history, and other relevant information. TransUnion also offers a variety of credit monitoring and identity protection services. 4. CRIF CRIF is another leading credit reporting agency operating in the Philippines. Its credit reports provide insights into an individual's or business's creditworthiness, including credit scores, payment history, and public records. CRIF also offers credit monitoring and vendor management services. 4. CIBI CIBI Information Inc. is a credit reporting agency based in the Philippines. They collect and maintain credit information on individuals and businesses. This information is used by lenders and other institutions to make informed decisions about lending and hiring. CIBI offers a credit report service that allows you to see your credit history and credit score. - Benefits of Credit Data Solutions Enhanced Credit Assessments: Credit data solutions provide a more comprehensive view of an individual's or business's creditworthiness, allowing lenders to make more accurate and informed lending decisions. Increased Financial Inclusion: By utilizing alternative data sources, credit data solutions can help expand access to credit for underserved populations who may not have traditional credit histories. Reduced Risk: Credit data solutions enable lenders to better assess and manage risk, reducing the likelihood of non-performing loans and improving portfolio performance. Improved Customer Experience: By streamlining the credit application process and providing real-time data, credit data solutions enhance the customer experience and reduce processing time. Conclusion Credit data
- June 1, 2024
- June 1, 2024