
- December 21, 2022
- December 21, 2022
How to use Smile API to expand your lending services
Why you should get started with expanding your lending services Philippine banks are upbeat on loan demand for the current quarter as post-pandemic optimism takes hold. Based on recent survey results, the BSP saw an uptick in demand for all household loans, including mortgages, credit card lines of credit, auto loans, and personal income financing. Consumers feel more secure about taking out these necessary forms of borrowing as conditions in domestic and global markets continue to improve. Filipinos receiving a loan have increased significantly from 29% in 2017 to 41% in 2019. This data is not surprising since more Filipinos recognize the need to manage their finances and learn more about the financial services accessible to them. Common reasons Filipinos apply for a loan; they are underbanked for educational purposes, medical expenses, setting up a business or investment, home and auto improvements, and debt consolidation. Thankfully there are helpful processes that increase operational efficiency and maximize profits as well as faster turnaround times and are more reliable and consistent in their results. - Image Source Automated and streamlined processes Automation and streamlining business processes are essential to increasing operational efficiency and maximizing profits. Automating manual tasks means less time is spent on administrative duties, increasing the amount of time available for productive activities. Streamlining processes removes redundancies and helps ensure business operations' smooth operation, yielding maximum output with minimum effort. Automated functions allow for much faster turnaround times, are more reliable and consistent in their results, increase transparency, and create a much higher level of customer service satisfaction. Implementing automated and streamlined processes can tremendously impact profit margins and productivity levels. - Image Source What is an automated loan processing? An automated loan processing system is a software-based solution that uses cutting-edge cloud and online technologies to digitize and automate all stages of the loan cycle. Unlike its predecessor, the automated loan processing system allows for faster processing and eliminates the need for documentation or face-to-face communication. Automated loan management systems are revolutionizing the way loans are managed. By streamlining processes and improving decision-making accuracy, these revolutionary systems help to increase efficiency and enhance security features, all while providing a 24/7 online assistance system for ultimate convenience. It's no wonder they're quickly becoming integral to the current loan administration! Advantages of Using Automation and Streamlined Processes Lending companies receive an incredible number of loan applications each week, yet only a fraction meet their lending criteria. By utilizing automated processing, banks and other lenders can quickly evaluate which applicants best fit these procedures- allowing them to make quick contact with those who qualify before underwriting loans in confidence. This system enables lenders to: Improve the speed and accuracy of loan applications to provide a better user experience. Increase the number of loan applications processed with existing resources. Reduce human error while making faster, higher-quality evaluation judgments. Create predictable, repeatable, and auditable processes to supp
- December 21, 2022
- December 21, 2022
- December 9, 2022
- December 9, 2022
Best Practices in Lending
In this blog post, we will explore in more detail several lending best practices, including understanding the borrower, assessing risk, and setting terms and conditions. We will also discuss the importance of proper documentation and consider the impact of technology on lending processes. With this information, organizations of all sizes can be sure that they are making the best decisions possible when it comes to lending. Check the borrower's credit history When it comes to best practices for lending, one of the most important steps is checking the borrower’s credit history. A borrower’s credit history is a record of their financial history, detailing how much debt they have and how regularly they’ve paid their bills in the past. By checking a borrower’s credit history, you can get an idea of their financial responsibility, which can be key to predicting whether or not they will repay the loan. It’s important to keep in mind that credit history is not the only factor to consider when making a lending decision, specially in markets where credit histories are not easily available or if the borrower simply doesn’t have it because they are either young, a non-resident, or do not have a bank account or credit card. Consider alternative credit data Alternative credit data refers to information about a person's creditworthiness that is not typically found in a traditional credit report. This can include things like employment history, income, bank transactions, utility payment history, rental payment history, and other financial data that may not be reported to the major credit bureaus. You can use alternative credit data to evaluate the creditworthiness of potential borrowers who may not have a traditional credit history, or to supplement the information in a traditional credit report. Using alternative credit data can help you make more informed decisions about whether to extend credit to a particular individual, and can also help borrowers who may not have access to traditional forms of credit to obtain the financing they need. Have a clear and detailed loan agreement When it comes to lending, one of the best practices to keep in mind is to have a clear and detailed loan agreement. A loan agreement should include the specifics of the loan, such as the loan amount, the interest rate, repayment terms, and any fees or penalties associated with the loan. Having a clear and detailed loan agreement helps ensure that all parties are on the same page and avoids any confusion or miscommunication. Additionally, having a loan agreement can help protect both the lender and the borrower in case of a dispute or misunderstanding. Set realistic repayment expectations When it comes to lending, setting realistic repayment expectations is key. First, you should determine the borrower’s ability to repay the amount requested. This includes evaluating their credit score, income, and other factors. Additionally, you should ensure the repayment schedule is feasible for the borrower. For example, if the borrower is a student with a limited income, you should consider providing a more flexible repayment schedule. Ultimately, setting realistic repayment expectations will help both you and the borrower maintain a healthy relationship. Monitor loan performance Monitoring loan performance is an essential part of best practices for lending. It helps you to assess whether a loan is performing as expected or
- December 9, 2022
- December 9, 2022
- December 2, 2022
- December 2, 2022
How APIs Enable Financial Inclusion
When most people think of APIs, they think of technology and how it helps developers build better websites and apps. That is, if they think of APIs at all - for most people it's yet another acronym or term that IT people keep talking about without ever really explaining what it is or what it does. But what if we told you that APIs are changing the way people interact with the world around them, and that includes financial institutions? In fact, APIs are one of the driving forces behind what is known as "open banking" or "open finance", a movement to make financial data more accessible so that people can make better-informed decisions about their money. APIs are playing a huge role in the world of finance and helping to promote financial inclusion for all. In this blog post, we'll take a look at what APIs are and how they're enabling open access to data and financial inclusion for everyone. We'll also go over some of the most common uses for APIs and their benefits, as well as some key takeaways on how APIs can help businesses and consumers with their everyday life. The Basics of an API API stands for “Application Programming Interface”. In simple terms, an API is a set of rules or protocols that determine how one piece of software can communicate with another. You can think of APIs like contracts. The API documentation is the agreement that if one party requests for data or service in a certain manner, the second party will respond in a specific manner as well. This simplifies the development of IT systems and applications, since even third parties, if given permission, can reliably request data or service regardless of the underlying software or hardware of the source. The provider of the data or service can upgrade their systems, change their architecture, or update their user interface, without impacting any third parties and partners who are using data they provide. The users of the data or service can do the same without needing hand-holding or significant assistance from the data provider. As long as both parties stay true to the agreement (which is the API documentation or specifications), it's business as usual for both of them regardless of changes happening on the other side of the API. APIs in Financial Inclusion and Open Data APIs play a big role in financial inclusion by providing access to data that was once siloed off and difficult to obtain. By making financial data available, APIs can help businesses make better decisions, empower consumers with more knowledge about their finances, and drive innovation in the financial sector. In the context of finance, APIs are what allows different financial institutions and services to share data with each other. For example, when you use a mobile banking app to check your account balance, that information is being pulled from the server via an API. When you use an e-wallet account to buy something from an online marketplace, the transaction takes place via APIs. API-enabled financial inclusion means that people who previously did not have access to traditional banking services can now use mobile apps and other digital platforms to make payments, transfer money, and save money. This is especially beneficial for people in developing countries who may not have a bank account or credit card. Common Uses for APIs for Financial Inclusion The wide adoption of APIs in the finance sector has led to the development of numerous
- December 2, 2022
- December 2, 2022
- November 29, 2022
- November 29, 2022
How Smile closes the generational gap by mitigating credit risk
As borrowers may fail to pay their debts following the agreed terms, credit risk can sometimes be inevitable for financial institutions. Recent studies show differences across age groups regarding financial needs, particularly in loan applications. For instance, while Millenials may have difficulty establishing themselves financially, early boomers can be the most economically stable and confident in managing their finances. - Image Source Smile closes this generational gap by mitigating credit risk. When lenders don’t have enough data to assess their borrowers, higher non-performing loans are evident and, therefore, a struggle for both parties. Which age range(s) are good-paying borrowers, and which are not? Those in their thirties and forties may be more willing to take risks with higher-interest rates due to their experience. Those over 60 tend to have a lower credit risk as they are more likely to pay off loans on time. Thus, when it comes to good-paying borrowers, financial institutions should look towards early boomers and those in their thirties or forties, as they offer the best long-term investment potentials thanks to their financial stability and willingness to take risks. The 2019 Financial Inclusion Survey also revealed that loans increased for both males and females, but more so for men, whose incidence nearly doubled from 15% in 2017 to 29% in 2019. And based on our research, which is a preview of our white paper, Filipinos typically apply for loans due to personal needs or to support their families. - Image Source On the contrary, younger generations, such as Millenials, might present a greater credit risk due to student loan debts and lack of experience. People in the credit risk field must be aware of this data to assess creditworthiness better and reduce high percentages of non-performing loans. Understanding each generation's different credit risk profiles will make it easier to determine loan decisions and take appropriate measures to minimize losses. Reasons for credit risk among different generations Credit risk is the potential for a borrower or counterparty to be unable to meet its obligations following agreed terms. Credit risk can have both direct and indirect impacts on an organization. The direct impact of credit risk may include losses from default or late payments on a loan, related interest or fees, and write-offs of bad debt. On the other hand, the indirect effects may include increased capital requirements, which can result in higher borrowing costs and lower liquidity if lenders become wary of extending credit. - Image Source Credit risk occurs when lenders lack further assessment for creditworthiness. Particular individuals are good-paying borrowers as long as they have a source of income, and younger individuals may find it hard to pay their debt since they don’t have a stable income. To simplify, credit risk happens when lenders need more data to assess their customers. How Smile can save lenders from credit risk regardless of age/generation To mitigate credit risk, financial institutions can employ strategies where they can evaluate the creditworthiness of potential borrowers. This can be through extensive background checks and financial analysis, diversifying their loan portfolios by minimizing overexposure to any borrower or type of asset class, and establishing sufficient recovery mechanisms to cover any losses incurred. Fina
- November 29, 2022
- November 29, 2022
- October 28, 2022
- October 28, 2022
Smile enables a 'decent' life for online Pinoy workers
Filipinos, primarily freelancers and gig economy employees, stand to benefit from the rise of internet work, both worldwide and locally. Undeniably, an increasing number of individuals are transitioning to online work for many reasons, such as no longer having to commute large distances and enjoying a better work-life balance. President Paolo Mercado of the Creative Economy Council of the Philippines (CECP) stated that 1.5 million Filipinos were already using international online platforms for freelancing services. - 2022 Philippines freelance market report Because online work is still relatively "young", unavoidable obstacles exist. Current policies may not account for and address the various challenges that internet employees face. This could be a huge opportunity for lenders and financial institutions to help gig economy workers who need access to global clients and payments in foreign currencies from anywhere in the world. The Obstacle Many Online Workers Face Recent research conducted by PIDS senior research fellow Ramonette Serafica and research analyst Queen Cel Oren supports this notion. This report was presented with the premise that the Philippines is "one of the most actively involved nations in online or platform work" and that the employment laws and access to financial services of online workers are among the hurdles in this field. As mentioned in their paper, ‘decent work’ is defined as productive labor and provides fair pay, security in the workplace, and social protection for families. Additionally, it should provide greater opportunities for personal growth and social integration. Given the variety of workers and types of online employment in the Philippines, the current policies may not be able to capture and solve the related issues. - Image Source Online workers, for instance, may have trouble acquiring access to several financial services since they do not have the same perks and features as self-employed individuals or full-time employees. One reason for this is that online workers do not have traditional jobs. Some of them do not work in the usual 9-5 schedule, which may not qualify them for a loan application. With assistance from the International Labour Organization (ILO), the Department of Labor and Employment (DOLE) is constantly developing new policies and programs to assist the nation in meeting its international responsibilities and achieving its medium-term objectives. These policies and initiatives focus on labor governance, labor standards, social dialogue, social protection, workplace rights, women and development, and workplace rights. In the emerging field of the FinTech Industry, Smile API is here to help resolve these hiccups. Where Smile Comes In Smile tackles this issue by providing the infrastructure for online employees' job and income data to be easily shared, facilitating access to better credit and other financial services. This is accomplished by granting authorized users access to this data and acting as a gateway or middleman between the data's owners and those who wish to utilize it, such as banks and other financial services businesses. - Smile API Wink Widget - Smile API Wink Widget Existing solutions cannot provide a complete picture of your borrowers' character, capacity, and capital. And as the global economy continues to shift online, it is more crucial than ever to have precise data on online workers' employ
- October 28, 2022
- October 28, 2022
- October 21, 2022
- October 21, 2022
Smile API Q3 2022: Product Updates and Highlights
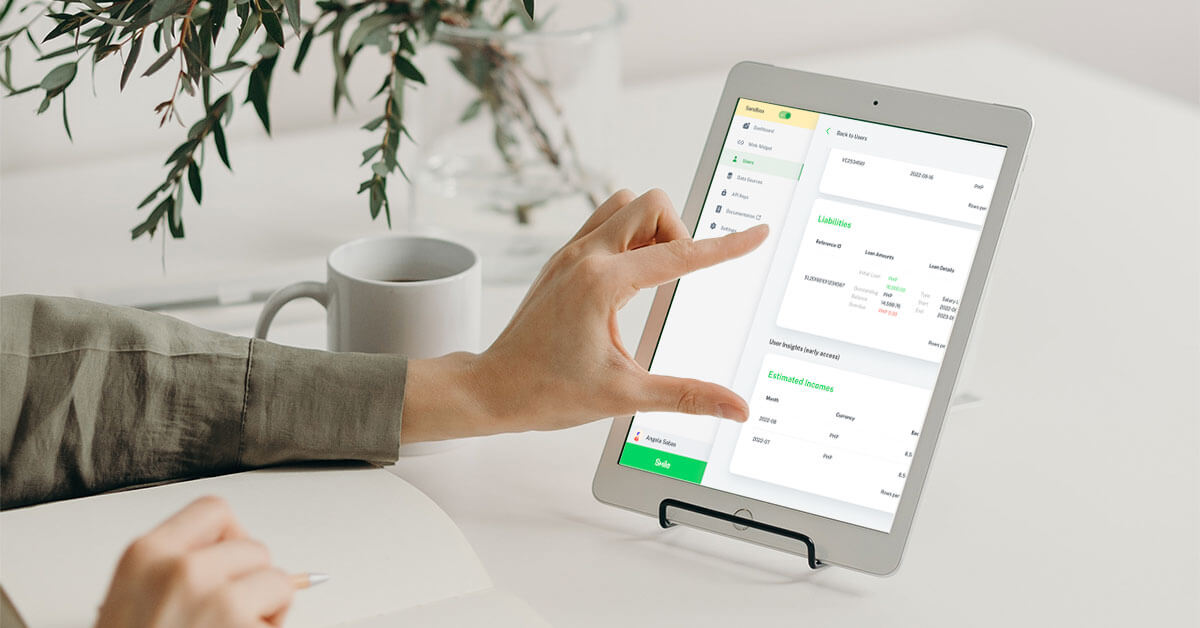
It's been another productive quarter at Smile API, and we're excited to share all the new features and improvements we've made to our platform. In this article, we'll outline each of the major product updates released in Q3 2022 and shed some light into improvements and fixes we've made under the hood to make sure we deliver the best value for customers and end-users alike. Highlights of Q3 2022 The product highlights for 2022's third quarter include: New APIs: Wink Widget improvements: New Developer Portal features and improvements: Documentation improvements: We'll go through each in more detail below. New APIs for Access to Better Data We've released new APIs to help you discover and use information from the data sources your customers choose to share with you. We've released the Estimated Income API, which provides an estimate of a person's current monthly income based on verifiable government-mandated contributions to social security and national health agencies. This API is currently in early access, which means that it may change before it becomes generally available. - Aside from estimates from contributions, we also surface estimates from alternative income sources that users may choose to share with financial institutions to further strengthen their credit worthiness. These income estimates from transactions on gig platforms are especially helpful when targeting the underbanked and gig economy workers. We've also started rolling out the Liabilities API this quarter, which provides information on your user's loans if they choose to share this data with you. - Lastly, making sure that end-users have full control of their data, we have also released the Account Revoke API, which allows users to completely revoke access to an account they have previously connected. - The Wink Widget SDK also automatically allows end users to revoke connected accounts. All account data is then removed from our system. Wink Widget SDK Improvements We've approached our Wink Widget with the mindset that it should meet financial organizations' requirements, ensure user experience and safety, and be as easy and quick to implement as possible. Aside from ensuring that users may revoke accounts easily to maintain control of their data, we've improved user experience with the display and presentation of our SDK's terms and conditions and privacy policies. Legalese are now shown within the SDK instead of being linked out, ensuring users won't feel threatened by unexpectedly being thrown out of the process of sharing their data to you. We've implemented additional callback functions for more robust error-handling and catching, as well as ensuring you get notified of pertinent user data information through our available webhooks. - Aside from adding webhooks for our new APIs, we've included webhooks for account locked events, and adopting an "at least once" delivery guarantee for notifications. Our SDK can now also pre-filter providers according to your requirements, if you wish to limit the data sources your users choose to share with you. New Developer Portal Features Our biggest update this quarter for the developer portal is the inclusion of a CV view of user data alongside the JSON formatted view. This makes it easier for both developers and risk professionals to quickly skim information that their users have shared with them, without the need for extra development. - An additio
- October 21, 2022
- October 21, 2022