
- March 21, 2022
- March 21, 2022
How to use the Smile API to Improve the KYC Process
KYC, or Know Your Customer, is a process that helps organizations verify the identity of their clients and customers. It's important because it ensures the legitimacy of customer-provided information, and ensures the organization stays on the right side of the law. The KYC process however, can be a time-consuming and tedious task for both the customer and the company. This is where the Smile API comes in. It can improve this process by providing a simple way to collect, aggregate, validate, and transmit customer information. Data Collection The Smile API provides an easy way to collect customer data that is stored in their employment platforms or documents. We get the data from the source, so that there is a higher probability of the reliability and accuracy of the data. If they are a gig worker that data can be from the freelance marketplace platform they have joined. If they are a full-time employee, it can be data from their payslips, employment insurance, or income tax document. All the user needs to do is either link their employment account by logging into their employment platform, or by uploading a photographed or scanned copy of their employment data if its in paper form. All of this data is secured with the permission of the user, and is kept secure at all times. Data Aggregation and Validation Smile aggregates data that is typically stored in different places and provides that in a simplified, unified way. Instead of trying to collect then process and analyze this data separately, we can aggregate it for you and present in a standard format or structure. For example, something as simple as a phone number or monetary amounts can be stored and shown in different ways by different data sources. We standardize these types of data points, using commonly used standards such as E.164 for phone numbers or ISO 4217 three-letter code for currencies, making aggregation and analysis of data easier. Data Transmission All the data that Smile collects, with the consent of the user, is digitized and sent in a standard format. This data is securely transmitted in an encrypted form. We send data via secure HTTP, the same method that banks use to send data to you when you open your bank account via a browser or mobile app. In this way, private, confidential data is only sent to the parties that the user trusts and no one else. Summary Data is the foundation of any financial service business. Without it, companies have a hard time making educated decisions. This is all the more important in the KYC process, where having inaccurate or deficient information can lead to substantial risk. The best way to get accurate, reliable data on customers' employment and income is by getting data from the source, and Smile’s API can help you do that.
- March 21, 2022
- March 21, 2022
- February 15, 2022
- February 15, 2022
The Advent of Alternative Credit Data
Towards the end of last year, the Philippine Central Bank or the Bangko Sentral ng Pilipinas (BSP) released a new piece of regulation that is likely to be implemented early this year. This new regulation applies to lending and financing companies and their online lending platforms (OLPs), and is designed to reduce the risk of Filipinos falling into debt traps, especially those who are in low-income brackets. Bangko Sentral ng Pilipinas (BSP) Circular No. 1133-2021 Here a quick summary of the new regulation: Target institutions: Financing Companies, Lending Companies incl. their OLPs Targeted Products: general-purpose loans, which (according to the SEC) can be used for any type of expense. The new rules apply to loans of PHP 10.000 and below, and to those with a targeted life cycle of 4 months or less. New interest rate cap: the new ceiling interest rate for these loans is 6% per month and including all additional fees, charges or penalties for late returns at a total maximum of 15% per month. Late fees and penalties: Late payment fees will be capped at a maximum of 5% percent per month, that is of the outstanding amount and there will also be a cost cap of 100% of the total amount borrowed including all interests, fees, charges and penalties. While the new regulation has the potential to be a relief for the nation’s low-income borrowers, it will also trigger lenders to start reconsidering their offerings to this group. The main point of concern becomes the lack of data for this segment. Low-income borrowers typically do not have a credit score or any data associated with them that can prove their credit worthiness. In the industry they are also known as “thin files”. The term refers to the thickness of the credit report of someone with little or no credit history. The credit history is traditionally a key ingredient in loan origination to determine if someone is willing and able to pay back a loan. Data is the Oil that Fuels Lending Up until now for many borrowers on OLPs a thin file was no reason to be rejected as high interest rates for all customers were creating ample income for lenders that could compensate them for the losses inflicted by those that turned out to be bad borrowers. The new regulation however pushes the industry to reinvent itself. As the new interest rate ceiling comes into play, revenue from interest income for lenders will be severely reduced. To keep profits at the same level, more scrutiny will be applied when reviewing and approving borrowers. A more sophisticated risk engine, the core element of every lending operation that determines the answer to the question of whether or not a lender should issue a loan to a borrower, becomes of paramount importance. And as the saying goes “data is the oil of the 21st century,” quite figuratively the fuel that feeds the risk engine has become data about the borrower. The only question lenders ask themselves is how to proceed in a market that is full with “thin files”? Could Alternative Data be a more Sustainable Source of Oil for Lenders? In the past, or in old fashioned lending markets, consumers were encouraged to “build a credit score” by taking out loans and swiping their credit cards, to be able to show the ability and willingness to repay a loan, which in turn was rewarded by an increased credit score. This was the key to getting access to an even higher loan with lower interest. While the system ha
- February 15, 2022
- February 15, 2022
- January 13, 2022
- January 13, 2022
Studies: APIs To Continue Improving Lives and Businesses
Although the term API or "Application Programming Interface" remains alien to most people, this way of allowing various apps and system software to talk to each other has made and continues to make positive impacts on quality of living and business success. You may not be aware of it, but you benefit from API just by searching in the Internet, on social media platforms, by using Google Maps in a rideshare app, or pay with e-wallets, among many others. Intended for greater data sharing and collaboration, the adoption of APIs by businesses and organizations across major industries has grown tremendously in 2021 and is projected to grow even further as companies advance their digital transformation efforts. Impact of APIs Across Industries According to the latest report by RapidAPI touted "The State of APIs Developer Survey 2021," a total of 2,200 professionals using APIs indicated that participating in the API economy is a top priority of their organization’s strategy. A detailed look at the responses of all the industries included in the survey showed that increased API usage was led by Financial Services (67.1%), followed by Technology (61.2%), Manufacturing (60%), Telecommunications (59.2%), Healthcare (55.6%), Professional Services (52.8%), and Government (44.4%). Yet according to a much larger scale survey conducted by API platform Postman – which inquired 28,000 developers and other tech pros – API-fueled innovation has helped companies respond to the pandemic; that the global API ecosystem is growing; that developers are spending more time than ever with APIs and that almost everyone believes investment of time and resources into APIs will increase or stay the same in their organizations for the next 12 months. What is an API? API, also referred to as Software Intermediary, is basically a set of rules that command how one application communicates with another easily. Simply put, API can be likened to a "glue" that links technologies. With APIs, data exchange methods, processes and workflows can be done in an automated way, at much less cost even as they provide better consumer experiences, enabling faster and more engaging transactions than traditional means. One common example that APIs make possible is making payments using e-wallets, or thru online bank transfer, or a credit card. Why APIs Matter Besides serving as a great tool that makes apps communicate with each other, APIs also allow developers to build innovative software more rapidly, aimed at improving services, enable innovations, therefore enriching business competitions. Proof of API-empowerment was realized at the height of the pandemic that caused tectonic shifts in market trends. Respondents in the Postman survey said they had to digitally (and quickly) modernize their organization to better serve changing markets, while some other respondents said they had to pivot their business entirely. Because of the power of APIs, organizations were able to implement changes in weeks or months that would have otherwise taken years. Common areas the companies in the report invested include e-commerce, customer support via chat and text, and contactless digital systems — all of which relied on APIs. Backing on API's importance, Iddo Gino, CEO and founder of RapidAPI, said that companies who are accelerating their transition to digital channels are turning to tools that make their developers more productive – especi
- January 13, 2022
- January 13, 2022
- January 6, 2022
- January 6, 2022
Reflections on our Product Journey so Far
It’s been an amazing journey so far here at Smile! It’s been less than than three months since our official launch, and barely a year since we started, and already our product has grown leaps and bounds thanks to the support and feedback from our partners and customers! As we come to the end of 2021, and look forward to 2022, I thought it would be useful to look back and reflect on where we have started, and where we plan to go. A look back: how we defined what we wanted to build Since day one, our vision for Smile API has been clear: to be “the one trusted source for employment and income data in Asia” We have also been very clear in the initial set of customers we wanted to serve: financial services providers who are dependent on this data to deliver their service or to lower their exposure to financial risk. We have found that there is significant inefficiency and friction in getting this kind of information, which has led to: Friction in verifying and onboarding customers, which in turn leads to poor customer experience Higher cost and effort in identity and employment verification, which in turn leads to higher interest rates for consumers Lack of reliable and consistent data on employment and income, which leads to greater risk for financial services providers Limited access to financial services, especially to those who do not have traditional employment, as the cost and risk for serving these types of customers may be too high using traditional means and criteria for verifications The last point in particular has been particularly helpful for us to further sharpen our initial product and value proposition at launch: “what if we could provide, at least in our first iteration, the employment and income data of that segment of the population that has been growing the fastest during the pandemic, but has been traditionally underserved simply because they do not fall under traditional categories of employment?” We refer of course to gig workers: those who engage in temporary and flexible jobs—either as their main source of income or as a source of additional income. By providing the means for them to easily share their information from the various digital gig platforms which have surged in popularity during the pandemic, we could empower them to have more control over their own data and gain access to better financial services and opportunities. What we then set out to do, after deciding to zero in on helping gig workers initially, was to then focus our efforts on a market that presented the most promise for the kind of constituents we wanted to serve. We found the Philippines in particular to be the most promising: it had a large, young and growing population of working age, a vibrant economy, and had experienced the largest growth in gig worker activity anywhere in the world during the pandemic. According to global payments firm Payoneer, the Philippines experienced “208% year-on-year growth” in the first half of 2020, outranking India (160%), Japan (87%), Australia (86%), and Hong Kong (79%). Building the product: from concept to launch With the problems we wanted to solve and value proposition to potential customers clear, and the constituents and market we wanted to serve defined, we then set out to embark on an aggressive product development process that took several months. We put together different ideas on how we can solve the problems that we ha
- January 6, 2022
- January 6, 2022
- December 28, 2021
- December 28, 2021
Product Update: Q4 2021
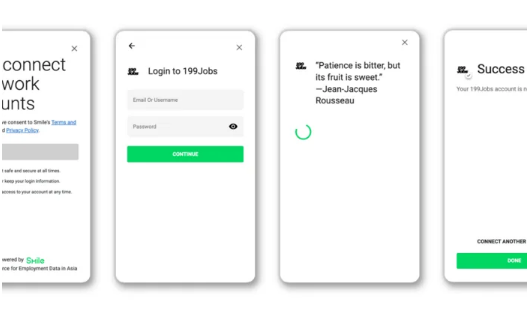
It’s been barely three months since our official launch, and already we have launched dozens of improvements and refinements to our product: including a more robust API, expanded employment data coverage, additional data points, additional developer implementation resources, and enhanced end-user experience. - When we launched, our focus was clear: be the trusted source for employment and income data in Asia, with the aim of enabling financial access and inclusion. We decided to initially start with gig workers, who tend to be underserved in this regard. Starting with the Philippines, we also started expanding our coverage into other countries such as Indonesia. Below is a summary of most notable enhancements in our product releases this quarter: Employment Data Coverage We have now expanded coverage to 26 employment data providers for gig workers. - Professional Services: - Transportation and Delivery: - Ecommerce Marketplaces - Disclaimer: All trademarks, trade names, company/product names, brands and logos appearing on this page are the property of their respective owners. Use of them is only for identification purposes and does not imply any association or affiliation with, or endorsement by the respective owners. Available Data Points for Each Platform Identity: we support various data points related to a user’s identity in the platform. The available data varies from platform to platform, but it can include the user’s full name, gender, birthdate, contact information (phone and/or email), and address. Transactions: if supported on the platform, we are able to share the user’s financial transactions on the platform, including the date of the transaction, currency, amount and description. Income amounts are positive, while expense amounts are negative. Ratings: we have also started rolling out the performance ratings users may have received on their employment platform. This can be a great leading indicator of the stability of employment of a gig worker. Ratings include the user’s aggregate score, the maximum possible score on the platform, and a calculated percentage score to provide a uniform basis of comparison across the different platforms. Implementation Resources We have added the following implementation resources to make it easier for developers to get started: Interactive documentation, with mocking services and sample code. A downloadable copy of the Smile API specification following Open API standards version 3.0 in Github A downloadable copy of our Postman Collection in Github Quickstart open source code to launch and try out our Wink Widget in any web app or in a local machine (find out more about our Wink Widget below). - End-user Experience - To make it easier for users to share their data, and for API developers to get started with our API, we have provided the Wink Widget Javascript SDK. The SDK allows the easy instantiation of our Wink Widget, which is a mechanism by which users can give their consent to have this personal data collected and transmitted to you or any party they trust on their behalf. This is all done in a simple, secure and seamless way. All of the different ways for the user to be able to successfully authenticate to their accounts, including dynamic support for the login credentials required (eg username, email, phone) on each platform, or any multi-factor authentication methods required by each platform are handl
- December 28, 2021
- December 28, 2021
- December 20, 2021
- December 20, 2021
Banking On Open Finance for Better Financial Inclusion
Are you one of many who remain to be underserved in the financial services industry? Are you still deemed by traditional banks and other financial institutions as a high-risk borrower even if you could be earning more than their regular employees? Chances are you have a decent source—or sources of income, but lacks proof-of-income. This experience is commonly heard among freelancers, gig workers and MSMEs or Micro, Small and Medium Enterprises. The missing link? Data! The availability of actual business transaction data or financial history to be exact. For instance, you might be successful in doing part-time or gig economy jobs maybe as a ride-share or food delivery driver, personal shopper, freelance writer, or tasker but if you can't share those data of your side-hustles or sidelines as actual proof of income, then asserting them by word of mouth or by letter won't mean a thing to banks and other lenders. That is why even with the emergence of Open Banking or "Open Bank Data" in the past few years, it hardly had any impact in making the unbanked or underserved eligible for the newly created financial products and services since they don't have banking data to connect to. Enter Open Finance In addressing the challenges faced by the greater unbanked and underserved populations in emerging economies like the Philippines, monetary authorities in different nations are looking into Open Finance as a key avenue for better financial inclusion. So what is Open Finance? Open Finance is a whole new ballgame in the financial services industry introducing a more holistic practice than its predecessor Open Banking since it deals with "finance data" as a whole and not just "bank data". Open Finance is deemed beneficial to the marginalized sector like the self employed, those working in family workshops, the jeepney drivers, rural workers like fisherfolks and farmers. It will enable them to share their financial history contained in the e-commerce and delivery platforms they use including within wallet apps they get paid through or remit money from. Rules of Play Set for Open Finance In the Philippines, Open Finance has been gaining traction. In fact the country's central bank or Bangko Sentral ng Pilipinas (BSP) is now implementing its Open Finance framework through its initiative Open Finance Oversight Committee (OFOC) which recently gained support from the World Bank and the International Finance Corporation (IFC). Launched last June, BSP's Open Finance framework encourages "consent-driven data portability, interoperability, and collaborative partnerships among financial institutions and third-party providers (TPPs)". BSP's leadership maintains that customers and consumers should have full control in the granting of access to their financial data since they are the owners of their transaction data. And as the sharing of consumer data improves within the community of financial institutions and TPPs, the BSP expects that industry players could tailor fit financial products and services for the underserved and marginalized. Among the wide variety of services that could be customized for the underserved include but not limited to: credit, investments, insurance, savings systems, pension funds, and private mortgages. In setting its own standards and procedures, the OFOC is tasked to promote a “non-discriminatory membership” approach in order to cover all relevant sectors such as banks, n
- December 20, 2021
- December 20, 2021